Vietnamese bond funds post higher returns but continue to see net outflows
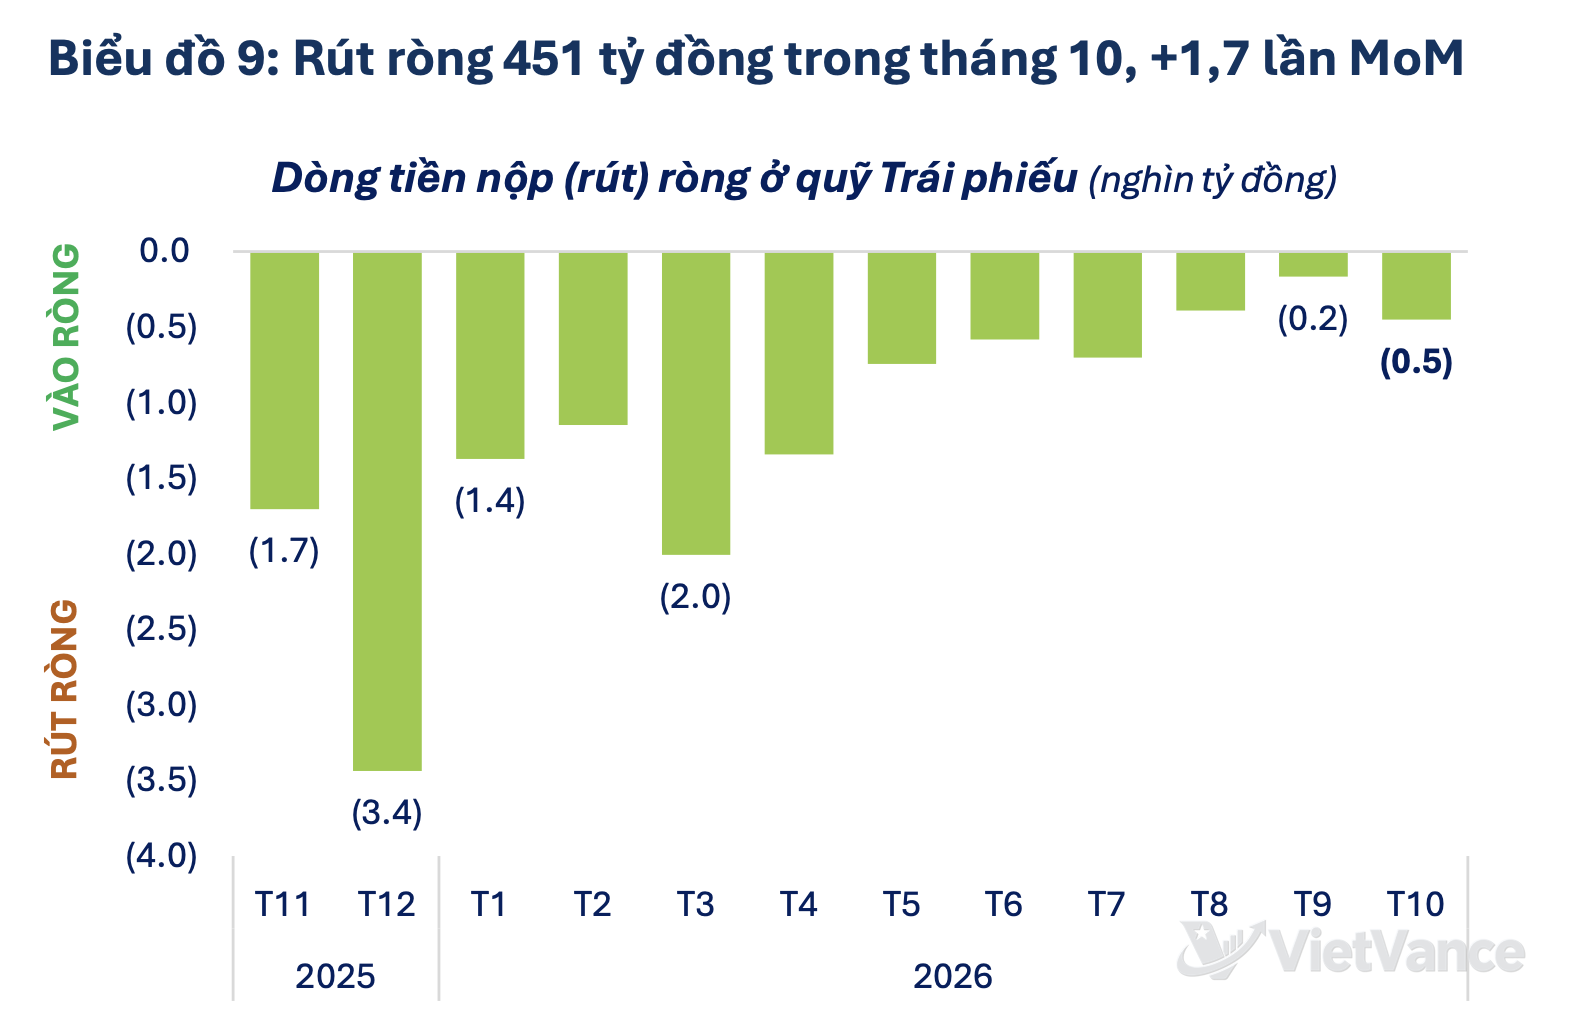
FiinGroup data show that Vietnamese bond funds returned an average of 0.57% in October 2026 and 5.2% over the first 10 months, outperforming the cited deposit rates. Yet some large funds continued to face redemptions, with TCBF recording net outflows of VND 6.043 trillion over the 10 months.

Vietnamese bond funds posted improved returns, but money continued to flow out. FiinGroup's October 2026 fund report shows that bond funds returned an average of 0.57% for the month, close to September's 0.58%. By the end of October, their average cumulative return for the first 10 months was 5.2%, up from 4.7% in the same period of 2025.
Vietnamese bond funds posted higher returns but continued to face pressure from net outflows.(VietVance)
Of the 28 bond funds tracked in October, 13 posted lower returns than in the previous month. VCBF-FIF returned 1.8% for the month, the highest among the funds listed; BVBF returned -0.6%, making it the only fund to record a negative return. FiinGroup attributed BVBF's performance mainly to unrealized losses caused by declines in the market prices of some corporate bonds in its portfolio.
Improved returns have yet to reverse the direction of fund flows. Over the first 10 months, TCBF recorded net outflows of VND 6.043 trillion, while DCBF and DCIP saw net outflows of VND 959 billion and VND 804 billion, respectively. In October alone, TCBF recorded a further VND 221 billion in net outflows. As of October 30, TCBF remained the largest of the funds tracked by net assets, at VND 4.148 trillion.
Bond funds' average return of 5.2% over the first 10 months was 0.8 percentage points higher than the average return over the same period on 12-month deposits at the four banks cited in the article. FiinGroup said current returns and their advantage over deposits were still insufficient to draw money back into bond funds. Investors choosing fixed-income products also need to consider credit and liquidity risks.
Source: VietVance