Are stocks down 30%–50% worth buying on the dip?
At an investment seminar in Vietnam, financial adviser Phan Lê Thành Long cautioned that a sharp fall in a stock’s price does not necessarily mean it is cheap. Investors should distinguish broad market shocks from problems within a company and assess risks and opportunities through its balance sheet, management and growth prospects. He also discussed the 2027 investment outlook for banking, oil and gas, and other sectors.

At a stock selection seminar organized by Chứng khoán VPS, Phan Lê Thành Long, chairman of Cộng đồng Cố vấn Tài chính Việt Nam (VWA), said a share price decline of several tens of percent is not, by itself, a reason to buy. Investors should first define their risk tolerance and growth goals, then screen prospective stocks for companies that fit their strategy, avoiding purchases driven by rumors or fear of missing out.
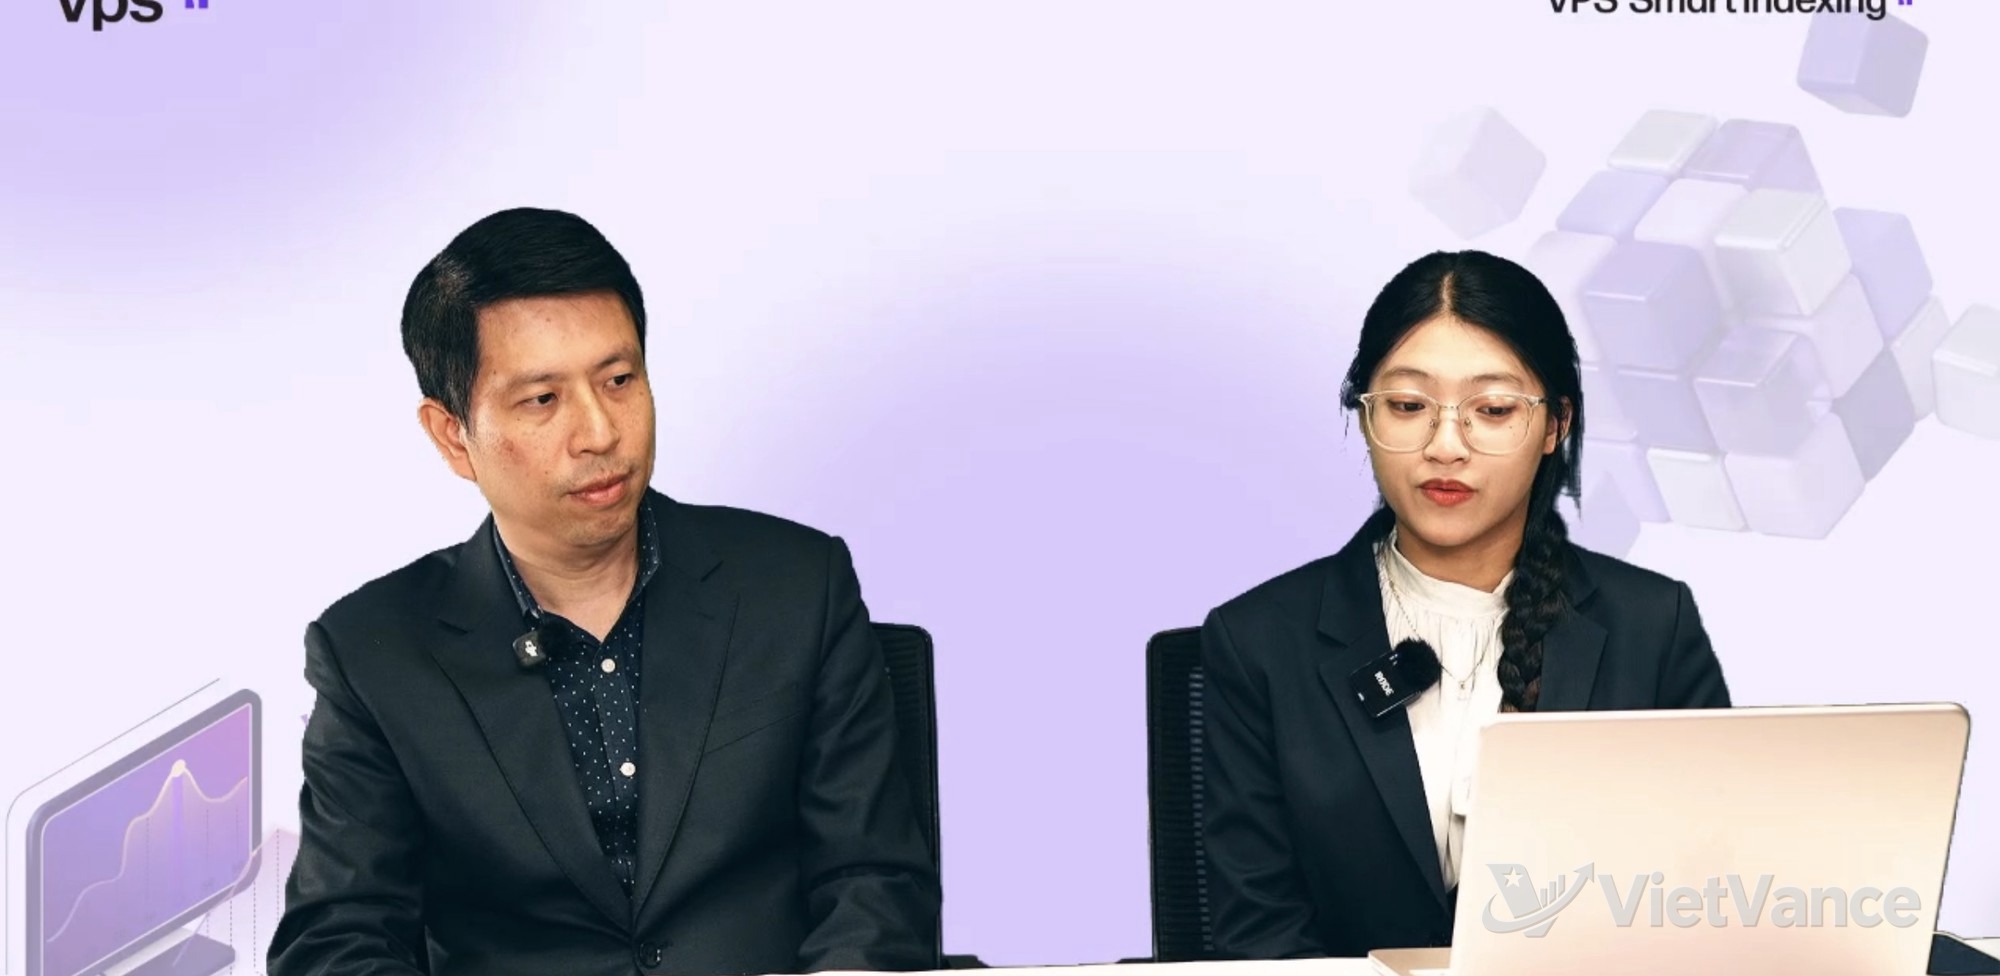
A scene from Chứng khoán VPS’s seminar on stock selection and portfolio building.(VietVance)
Long said it is crucial to understand why a stock has fallen. The reciprocal tariff shock in April 2025 put broad pressure on the market, and even stocks with strong fundamentals may have been sold. If a company’s long-term prospects have not changed significantly, investors could consider buying. But if the decline stems from legal risks, liquidity difficulties or weakening operations, the stock may continue to lose value even after a steep fall.
When analyzing a company, he advised paying close attention to its balance sheet rather than focusing only on current revenue and profit. For example, a sudden rise in inventory without supporting business expansion or sales prospects may signal risks ahead. Investors in real estate companies should also examine inventory, business cooperation arrangements, entrusted investments and advance payments to sellers. Increases in these items may create a need for additional borrowing and put pressure on financing costs. He said such changes can help investors spot operating risks one to three quarters in advance.
Looking ahead to 2027, he expects banking may enter a new credit cycle, although net interest margins will be under pressure and banks’ performance will diverge. He is also positive about the outlook for oil and gas, while cautioning that its share prices are highly sensitive to oil price cycles. Steel companies still need to be assessed individually. In retail, investors should exclude inflation when assessing real growth, while the effects of public investment may take time to show up in consumption and business activity.
Source: VietVance