Vietnam Sets 0.2% Tax Rate on Idle Land From 2027
Vietnam’s National Assembly passed tax amendments on November 20 that will apply a 0.2% tax rate to all idle land from July 1, 2027, without an area limit. The amendments also raise the revenue threshold for simplified tax calculations for businesses and household businesses. Lawmakers also approved amendments to the Investment Law covering special investment incentives.

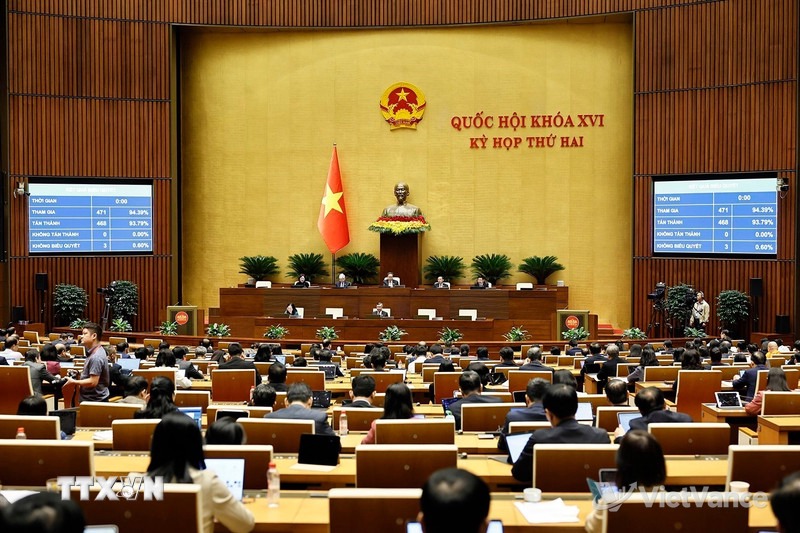
On the afternoon of November 20, Vietnam’s National Assembly passed amendments to three tax laws covering corporate income tax, non-agricultural land use tax and personal income tax, with more than 99% of participating deputies voting in favor. Under the amendments, idle land will be taxed at 0.2% without an area limit; the rate will apply to its entire area. The provision takes effect on July 1, 2027.
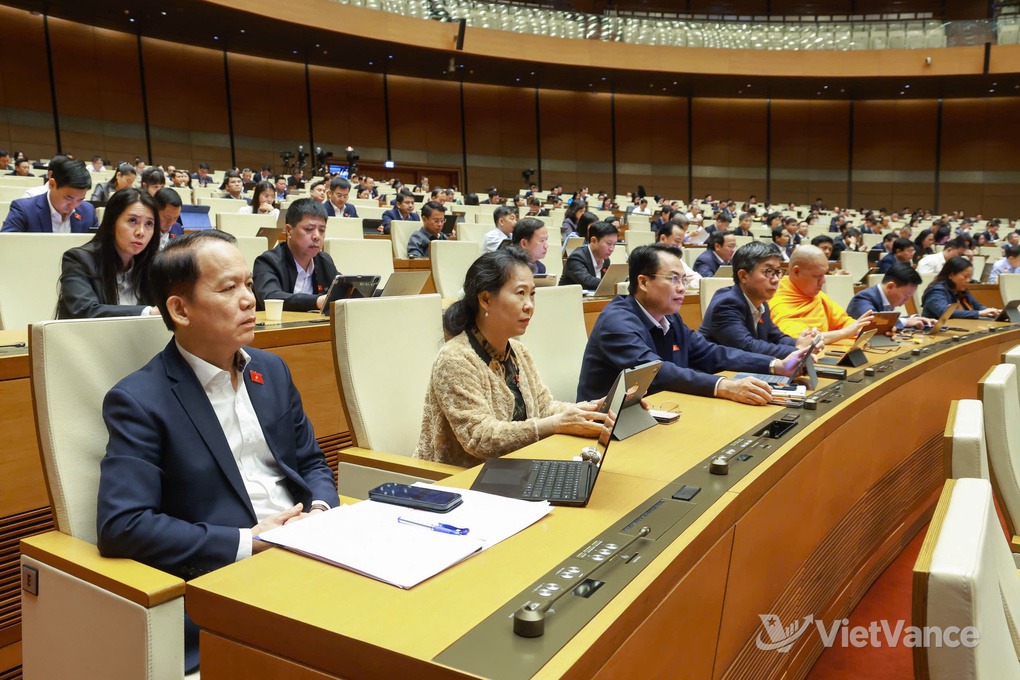
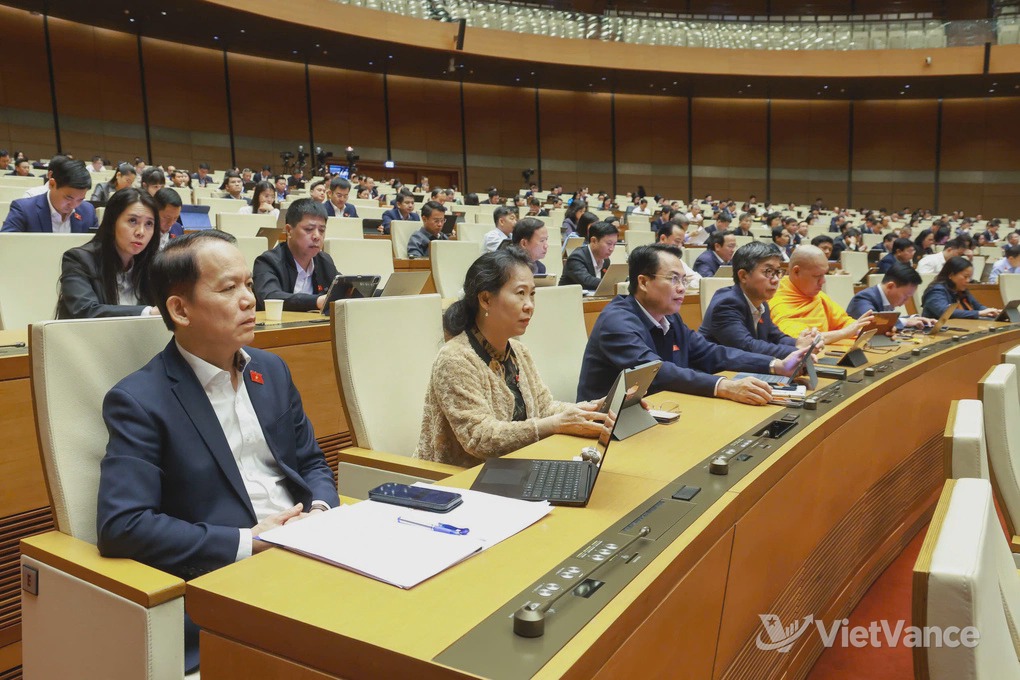
Deputies at a session of Vietnam’s National Assembly on the afternoon of November 20.(VietVance)
The amended non-agricultural land use tax law also sets a 0.15% tax rate for land used for an improper purpose. Idle land will be identified under land law provisions. During earlier discussions, some called for exemptions where land lies idle because of force majeure or circumstances beyond the owner’s control, and for the criteria and time periods used to identify idle land to be made public.
A draft amendment to the Land Law under review proposes that land allocated or leased by the state may be classified as idle if it remains unused for a specified continuous period. Land allocated or leased for an investment project may also be classified as idle if the project is not completed and the land put to use on schedule. The Vietnamese government said it would ask the Ministry of Finance and the Ministry of Agriculture and Environment to clarify the criteria, as well as cases eligible for extensions or exemptions due to objective circumstances, as they finalize the draft and related documents.
The income tax amendments raise the annual revenue threshold for simplified tax calculations to 10 billion Vietnamese dong. Businesses with annual revenue of no more than that amount may choose to calculate tax by applying a tax rate to revenue minus costs, or as a percentage of revenue. Previously, the revenue percentage method was available to businesses with annual revenue below 3 billion dong. The threshold for individuals and household businesses using the “tax rate multiplied by revenue” method also rises from 3 billion to 10 billion dong. These provisions take effect on January 1, 2027.
The National Assembly also passed amendments to the Investment Law that day with nearly 94% voting in favor, authorizing the government to set special investment incentives and support measures. The three groups of projects covered include innovation centers, big data centers, cloud computing and 5G infrastructure; semiconductor chip research and development, design, manufacturing and testing, and artificial intelligence centers; and international logistics service centers and energy and commodity storage facilities serving regional and international markets. The law takes effect on March 31, 2027.
Source: VietVance