Hanoi Homebuyers Face Relocation and Loan Repayment Pressures at Projects with Violations
Hanoi plans a special mechanism to address 12 projects with violations developed by Muong Thanh Group. Some buyers fear that, if their homes are demolished, compensation may not cover their outstanding loans and replacement homes. Legal experts say demolition does not automatically end repayment obligations, while compensation and loan arrangements remain unclear.

Hanoi plans to use a special mechanism to address violations at 12 projects developed by Muong Thanh Group. Some residents still repaying home loans worry that, if their homes must ultimately be demolished, compensation may not be enough to pay off their loans and buy replacement homes. Whether the homes will be demolished and what compensation will be offered remain unclear.
Hanoi resident Thu Hiền bought a 67-square-meter apartment in the HH3B building at the HH Linh Đàm residential complex in 2015 for nearly VND 1.1 billion. Nearly VND 750 million of the purchase was financed through a preferential 15-year loan at an annual interest rate of 5%. She says she still owes about VND 250 million in loan principal and worries about the cost of renting and buying another home if she has to relocate.
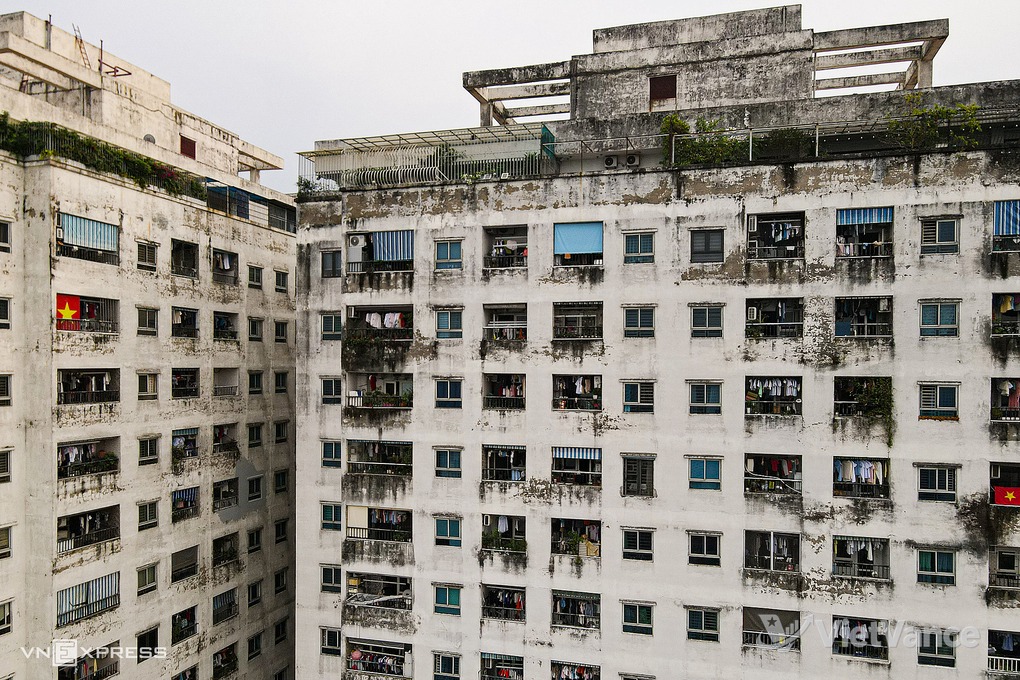
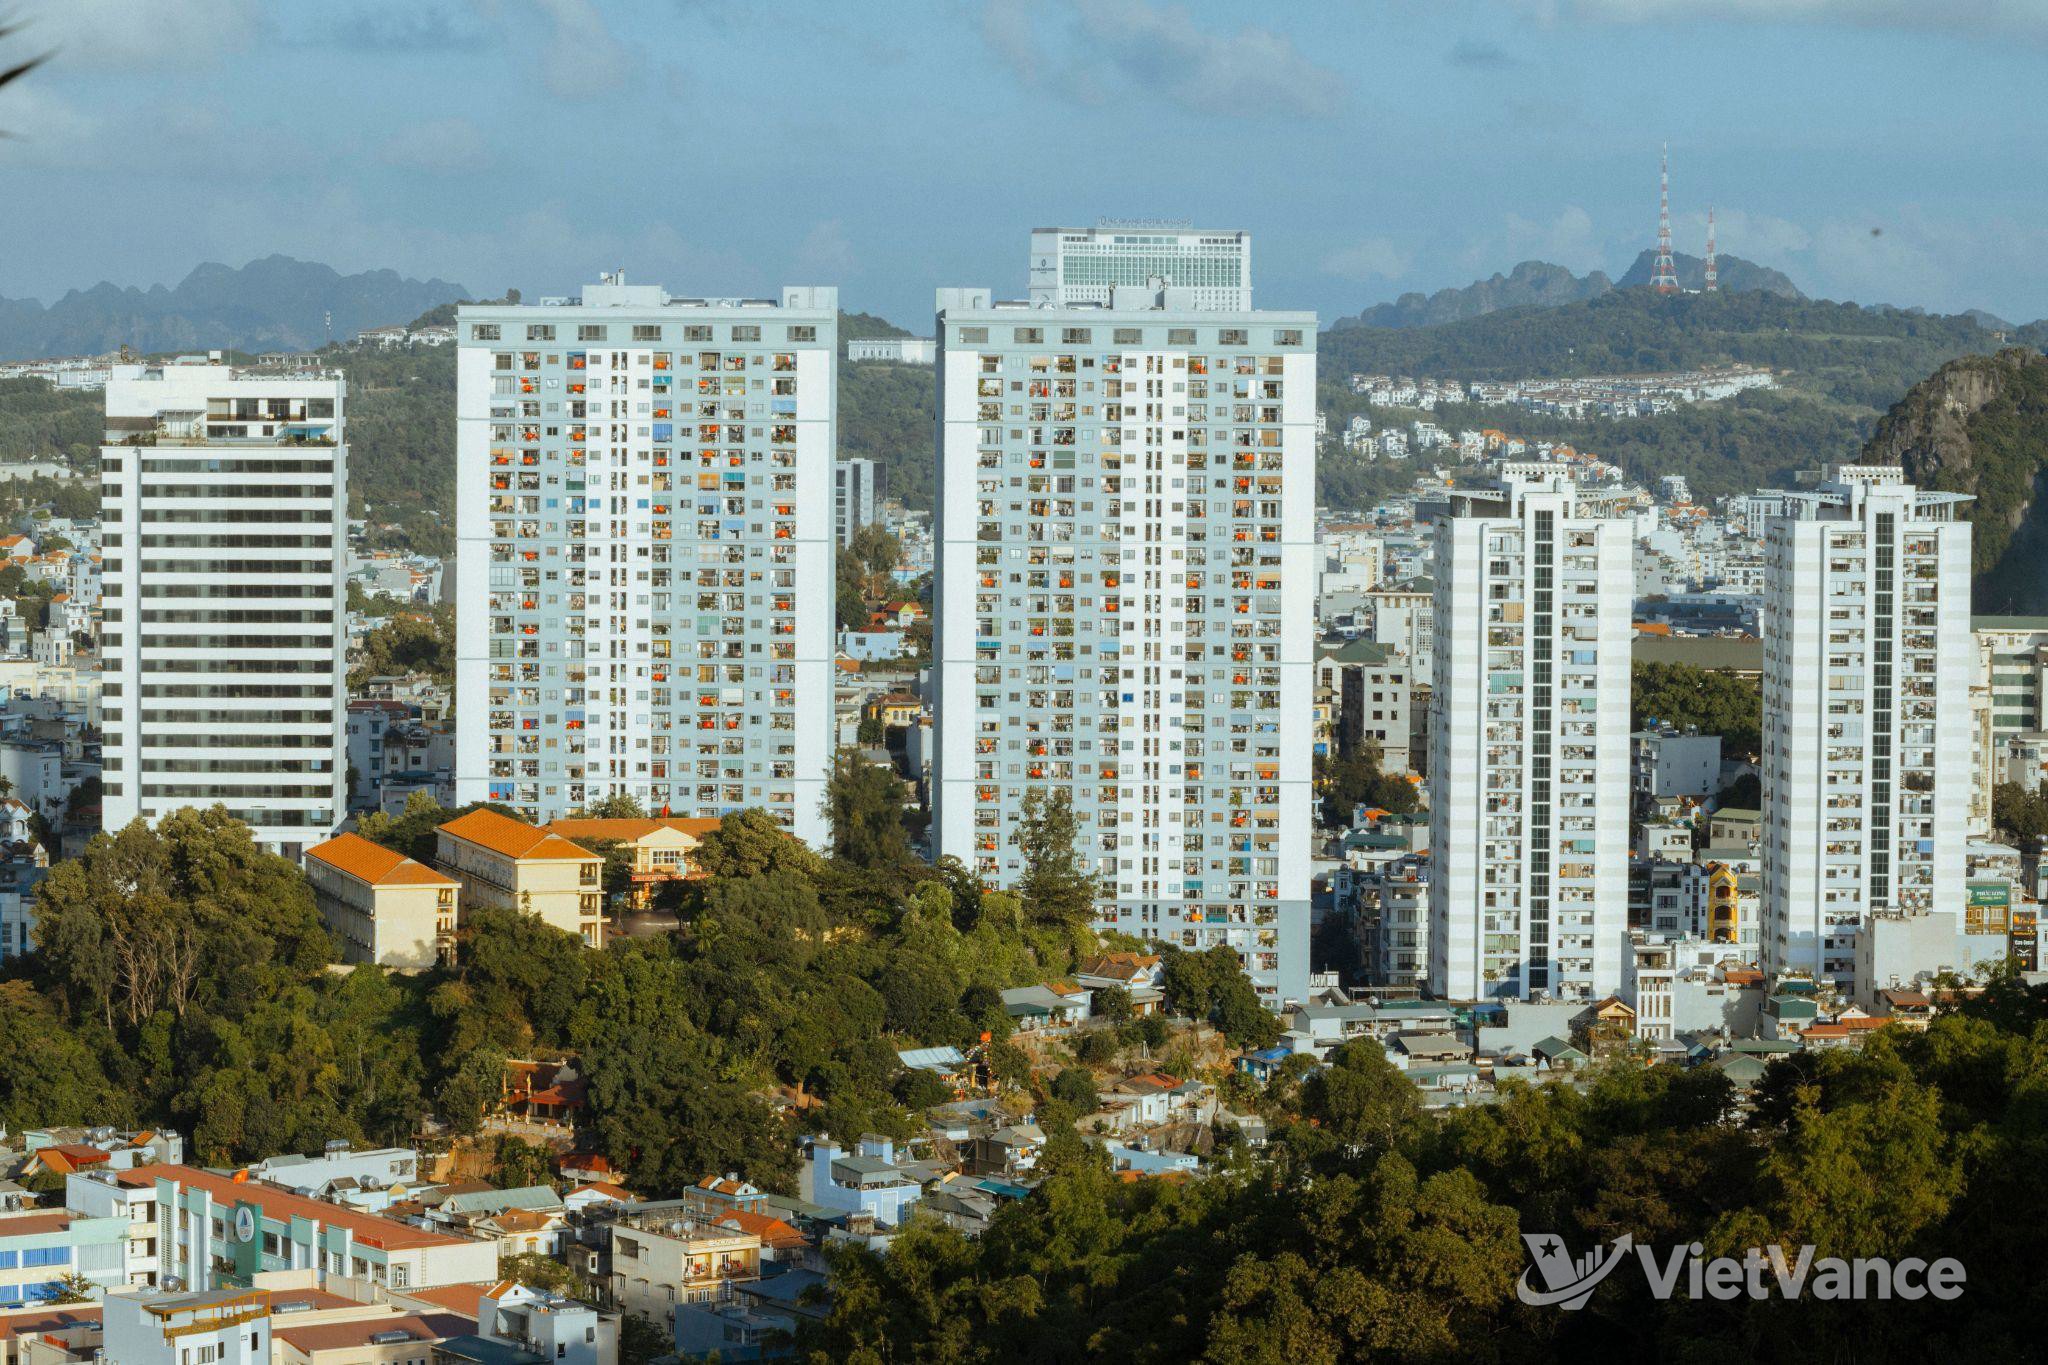
The HH Linh Đàm residential complex in Hanoi in November 2026.(VietVance)
Another buyer, Nguyễn Thảo, purchased a 40-square-meter apartment in the CT8B building at the Đại Thanh urban area in late 2025 for VND 2.6 billion, borrowing 60% of the purchase price from a bank. After the preferential period, the annual interest rate rose to 13%, and her first monthly principal and interest payment exceeded VND 21 million. After learning that the CT8B and CT10B buildings had violations and could be demolished, she became concerned that compensation would be insufficient while she would still have to repay the loan.
Lawyer Phạm Thanh Tuấn said borrowers’ repayment obligations do not automatically end if apartments used as collateral are demolished. He recommended that the authorities, residents and banks coordinate demolition, compensation and loan arrangements to prevent residents from losing their homes before receiving compensation. Phạm Đức Toản, general director of EZ Property, said compensation valuations should account for when homes were purchased, their legally approved floor area and reasonable costs incurred by residents. Arrangements should also clarify how mortgaged properties will be released from collateral and how remaining debt will be handled.
Economist Đinh Trọng Thịnh suggested that banks consider allowing residents to continue their existing loans while substituting replacement apartments as collateral. Repayment terms could also be adjusted for those facing financial difficulties because of relocation. He said such arrangements would require coordination by local authorities and guidance from the State Bank of Vietnam.
Source: VietVance