Vietnamese Bank Stocks Near Historic Valuation Lows as Asset Quality Faces a 2027 Test
SGI Capital’s October 2026 report says Vietnamese bank stock valuations are near historic lows, but overdue and nonperforming loans are rising, while the provision coverage ratio has fallen to a 10-year low. Expanding real estate credit and pressure on net interest margins could affect earnings in 2027, putting differences in asset quality among banks in focus.

In its October 2026 report, SGI Capital said the price-to-earnings and price-to-book ratios of Vietnamese bank stocks had approached historic lows, but low valuations came with pressure on asset quality and earnings. The firm said the stocks’ subsequent performance would still depend on each bank’s ability to control credit risk and sustain profits.
The report showed that Group 2 loans and nonperforming loans in the banking system had risen for three consecutive quarters, approaching the highs recorded at the end of 2022. Although provisioning expenses increased in the third quarter of 2026, the nonperforming loan provision coverage ratio still fell to its lowest level in 10 years. SGI Capital said a weaker provision buffer could affect banks’ ability to sustain profits in the coming quarters.
By the end of the third quarter of 2026, credit for real estate investment and business activities had grown by more than 25%, more than twice the pace of overall credit growth, while demand for home loans was nearly flat. Real estate credit accounted for more than 25% of the banking system’s total outstanding loans. SGI Capital said that if real estate transactions weakened and the market’s capacity to absorb supply failed to improve as supply increased in 2027–2028, the risks of capital being tied up and nonperforming loans could rise.
Lower lending rates could also squeeze banks’ net interest margins, especially at banks whose funding costs do not fall in step. SGI Capital said narrowing net interest margins, slower credit growth and higher provisioning expenses could together weigh on banking sector profits in 2027; the actual impact would still depend on each bank’s loan portfolio quality and control of nonperforming loans.
At an investment forum on November 12, 2026, Trần Thị Khánh Hiền, head of research at MB Securities (MBS), said net interest margins were unlikely to become a significant growth driver for banks, while the ability to control credit risk could lead to differences in valuations. She said banks that genuinely improve their asset quality in 2027 would merit higher valuations.
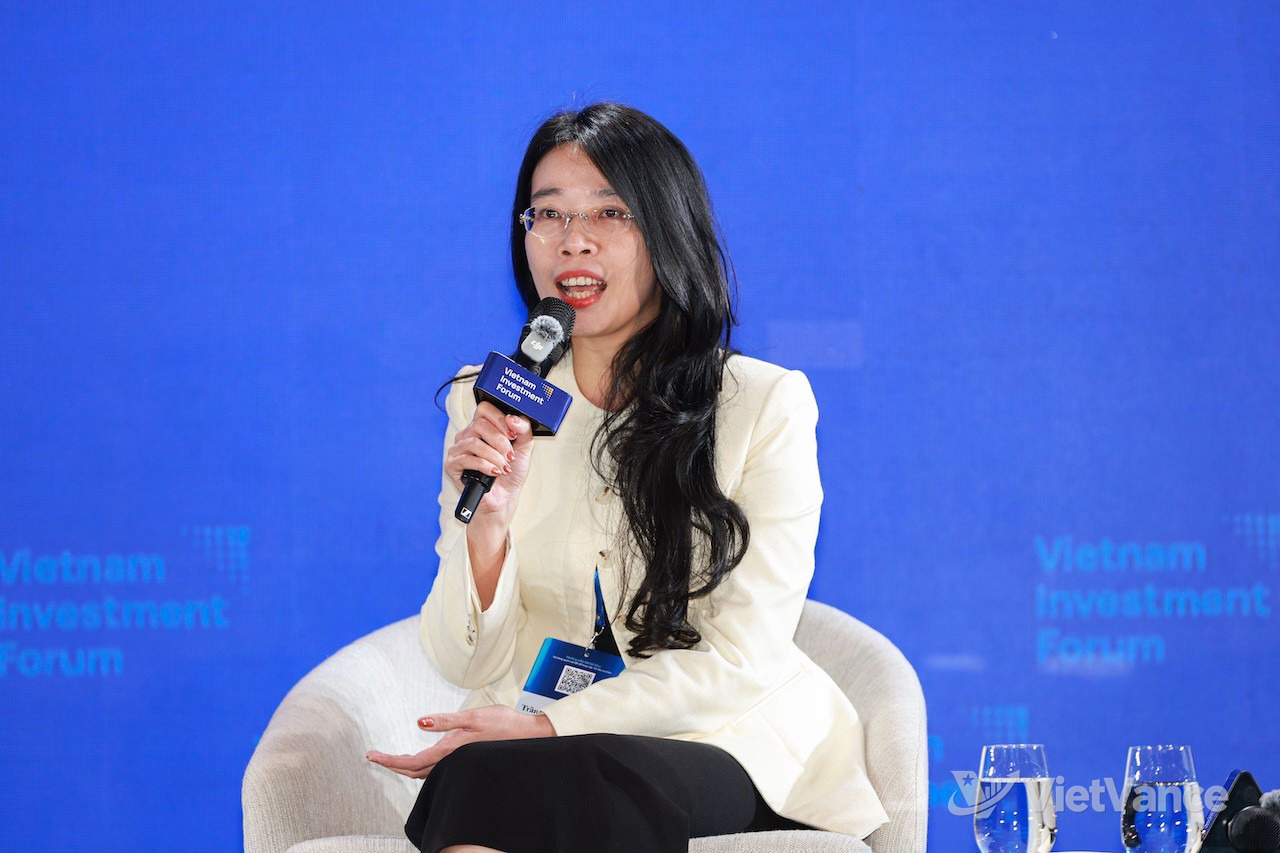
Trần Thị Khánh Hiền, head of research at MB Securities (MBS).(VietVance)
Source: VietVance