Vietnam Proposes Cutting Some Tax Penalties for Business Households by Up to 85%
Vietnam’s Ministry of Finance has submitted a draft resolution that would cut certain tax procedure penalties for eligible business households and individual business operators by up to 85%. It would also waive some filing requirements for taxpayers with no tax obligations and simplify tax code closure for entities that have long ceased operating.

Vietnam’s Ministry of Finance has submitted a draft resolution to the government proposing to reduce by up to 85% penalties for tax procedure violations by business households and individual business operators taxed under the declaration method. The violations include late tax filings and failure to prepare or submit invoice notices or reports as required. Penalties would fall to 15% of the usual rate; an earlier proposal would have reduced them to 50%. Those eligible would have to submit all outstanding tax filings, notices and invoice reports. The policy is proposed to run from November 21, 2026, through June 30, 2028.
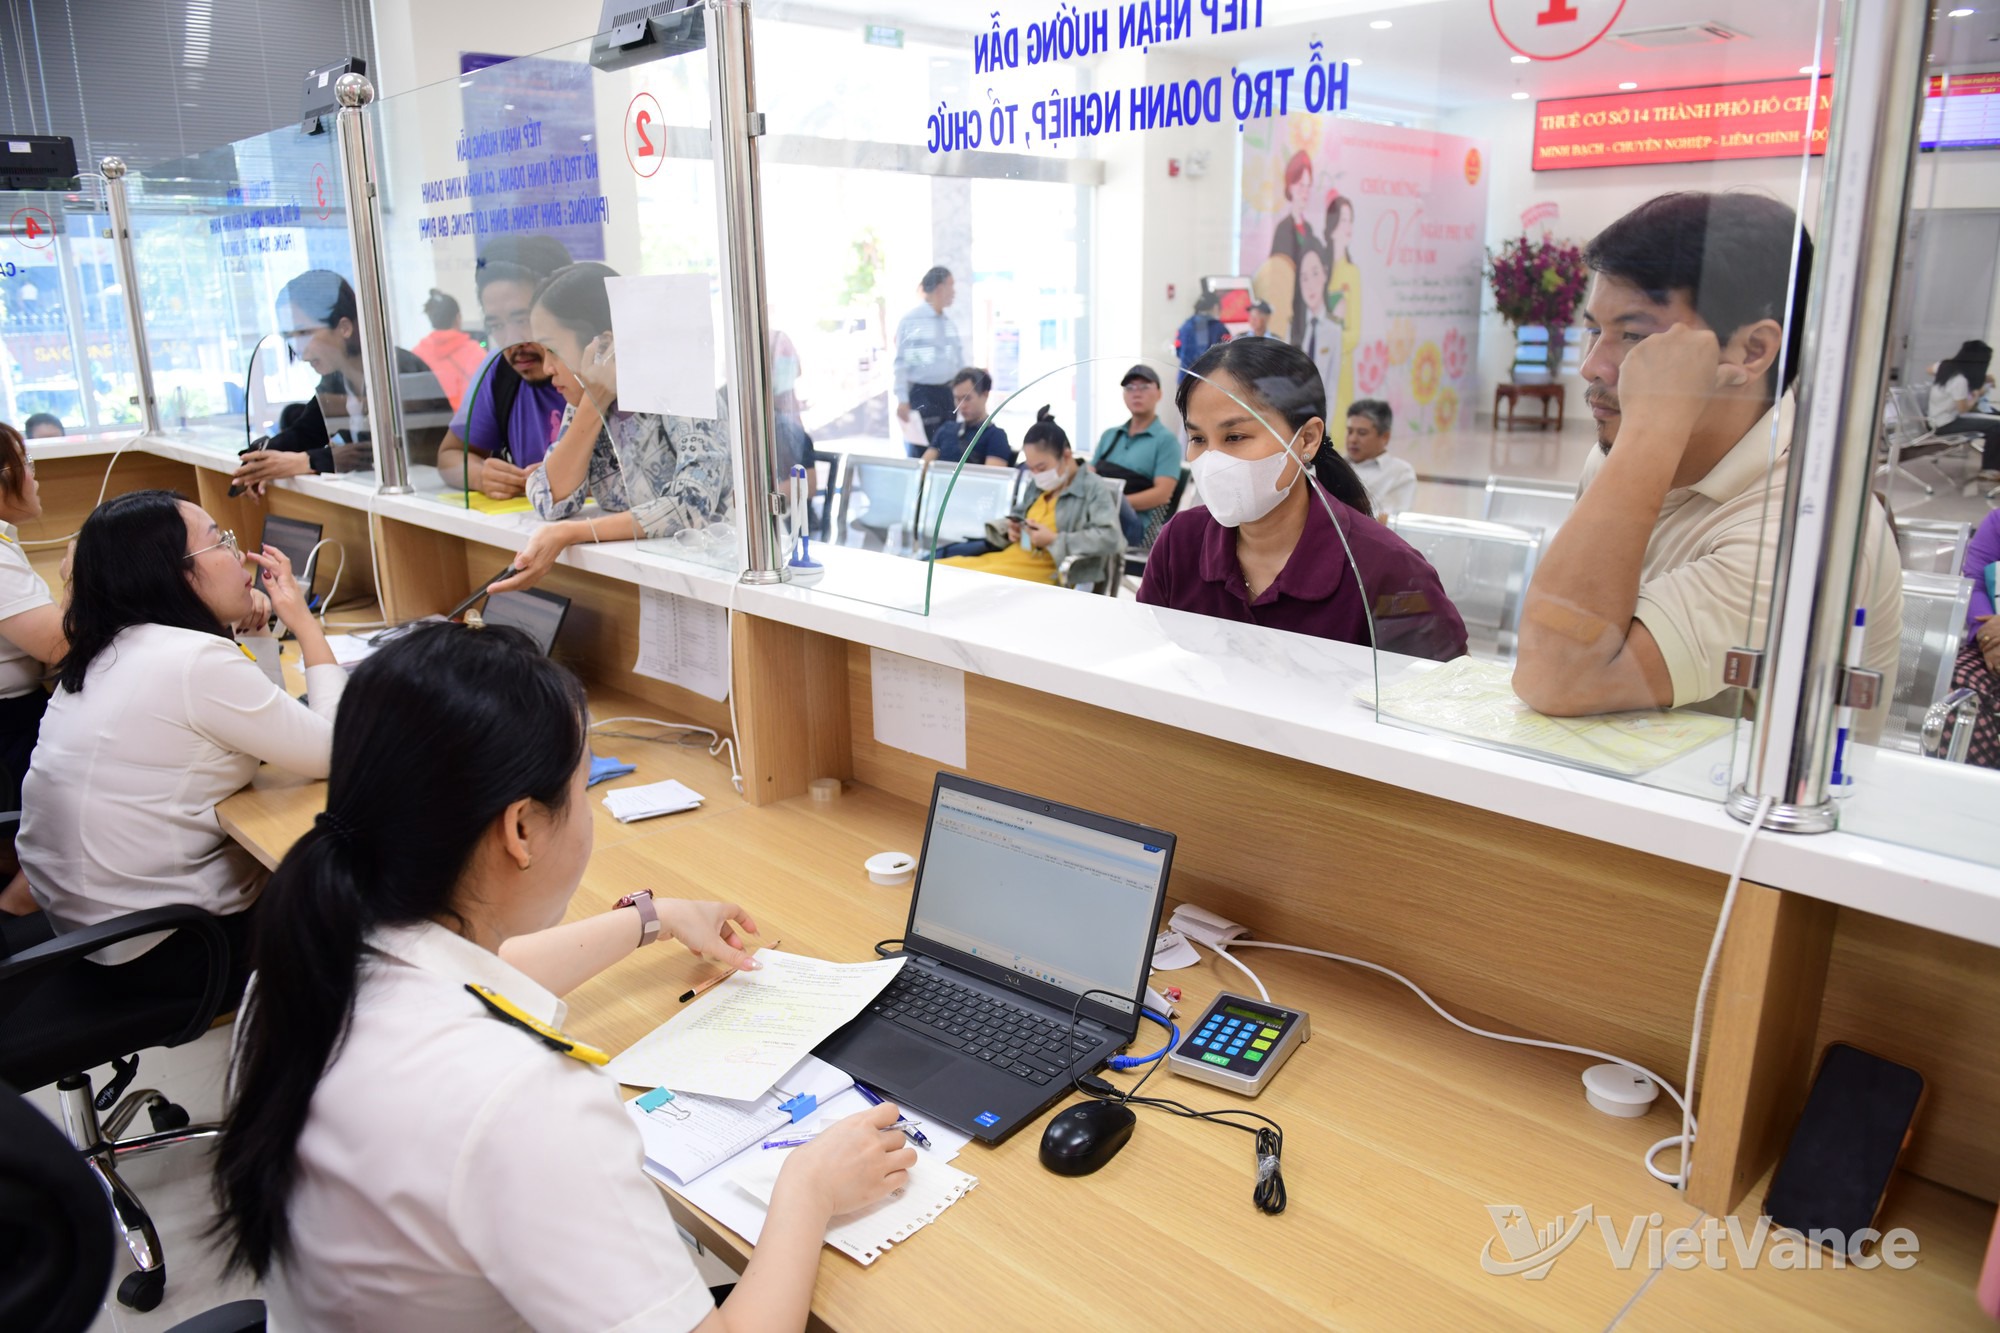
Vietnam’s Ministry of Finance has proposed reducing penalties for tax procedure violations by some business households and individual business operators.(VietVance)
The draft would exempt eligible business households and individual business operators taxed under the presumptive method from penalties for tax procedure violations. For other taxpayers, including companies, penalties would be 30% of the usual rate if they complete their filings between November 21, 2026, and June 30, 2027; 50% if they do so in the second half of 2027; and 70% if they do so in the first half of 2028. The policy would not apply to tax evasion or tax fraud, or to taxpayers undergoing inspections, investigations or judicial proceedings over those acts.
For periods in which no tax obligations arose, the draft would waive tax filing requirements for eligible taxpayers. If they did not use invoices during the exempt period, they would also not have to submit invoice reports for relevant periods before July 1, 2022. Taxpayers would have to make a declaration and bear legal responsibility for it. Those who applied to restore or close a tax code before November 21, 2026, but whose applications remain unresolved could submit an additional declaration without filing a new application.
The draft would also allow tax authorities to close the tax codes of taxpayers that, as of June 30, 2028, had ceased operating or had not operated at their registered address for at least 10 consecutive years. Conditions include having no outstanding tax debt at the time of closure and no unresolved indications of tax evasion or fraud. Tax authorities would have to publish a proposed closure list for 30 days beforehand. The ministry gave the example of a company that had been inactive for 10 years: closing its tax code could require 50 additional tax filings and about 55 million Vietnamese dong in related fees and penalties.
Source: VietVance