Vietnam Allows EVN to Use After-Tax Profits to Cover Costs of Failed Power Projects
Vietnam’s Decree No. 407/2026 allows Vietnam Electricity (EVN) to use after-tax profits to cover eligible investment costs for power projects that cannot proceed because of planning adjustments or policy changes. The costs may be allocated over up to five years. The decree also sets rules for allocating other costs and transferring assets.

The Vietnamese government has issued Decree No. 407/2026, setting out special operating and financial management rules for the parent company of Vietnam Electricity (EVN). Under the decree, eligible preparation and investment costs already incurred for power projects that cannot proceed because of planning adjustments or policy changes may be covered from after-tax profits. These costs are not deductible when calculating taxable income for corporate income tax purposes.
The rules apply when an authorized agency adjusts a plan, leaving a project ineligible to proceed; or when an authorized agency issues or amends a policy that changes investment conditions, and that change is the direct and decisive reason the project cannot proceed. The costs must be supported by documents assessing the impact of the planning or policy change, along with the relevant acceptance, settlement and independent audit records.
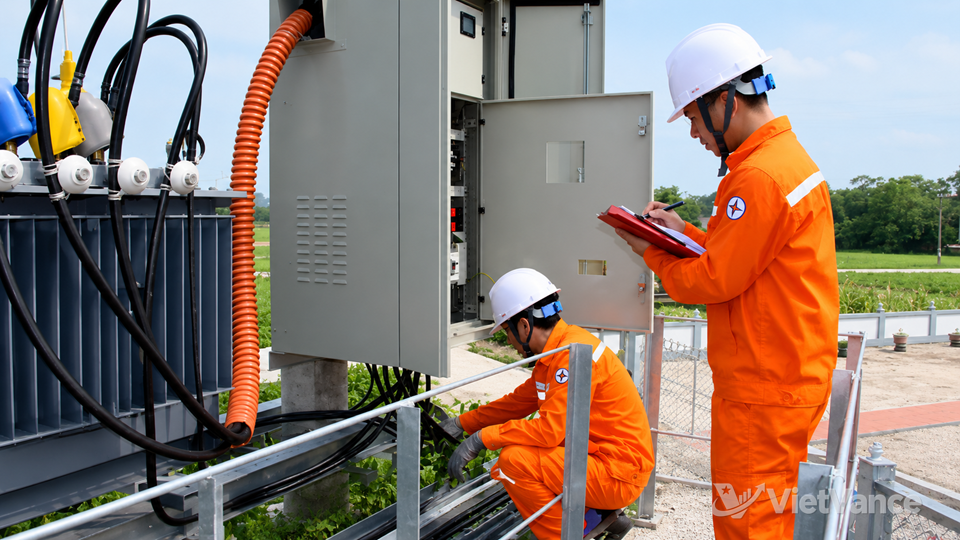
EVN may use after-tax profits, as prescribed, to cover eligible investment costs of failed power projects.(VietVance)
After an independent auditor issues an unqualified opinion on the settlement value, EVN may set an allocation period of up to five years from the date its Members’ Council approves the project as eligible for settlement. The decree also allows exchange-rate differences accumulated during construction of projects under the national power development plan to be allocated to financial income or expenses. The allocation period for expenses may not exceed five years from the start of operations; for nationally important projects, it may not exceed the loan repayment period.
Electricity meter costs may be allocated over no more than five years from when they arise. Repair costs for power facilities caused by external events such as natural disasters or fires may be allocated over no more than three years from when they arise if they reduce profit below the planned level or cause a loss. The amount allocated is calculated after deducting insurance compensation and any other support funds.
For asset management, EVN’s Members’ Council may decide to transfer projects and assets between EVN and its wholly owned subsidiaries at book value, without revaluation. When EVN takes over power facilities developed through public-private partnerships and information on their original and remaining asset values is unavailable, their value may be provisionally set at 20% of the project’s investment value, with valuation then completed as required. This provisional method also applies to facilities taken over before the decree took effect whose valuation has yet to be completed.
Source: VietVance