Vietnam’s 0.2% tax rate on idle land to take effect in July 2027
Vietnam’s National Assembly passed tax law amendments on November 20, 2026. A 0.2% tax rate on idle land will take effect on July 1, 2027. From the 2027 tax year, the revenue threshold for businesses and individual business operators to choose an income tax calculation method will rise from VND 3 billion to VND 10 billion.

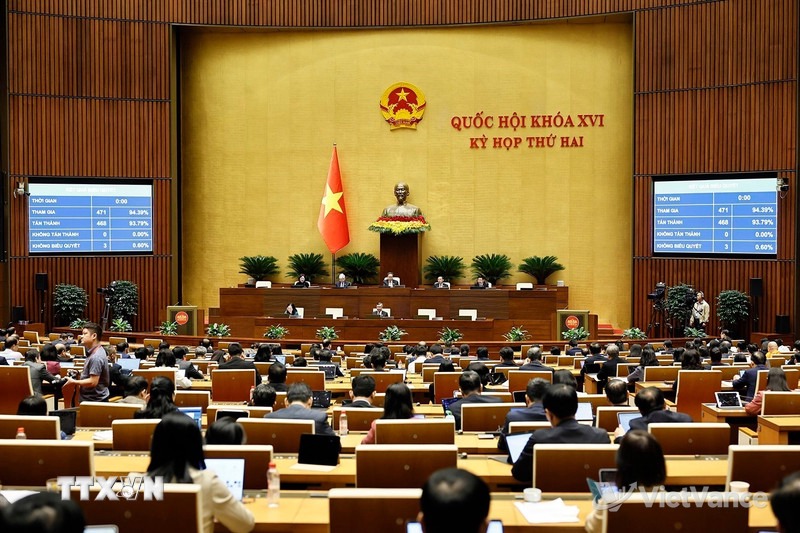
Vietnam’s National Assembly passed amendments to the laws on corporate income tax, non-agricultural land use tax and personal income tax on November 20, 2026, with 475 of the 477 deputies who voted in favor. The law has four articles and generally takes effect on January 1, 2027; the provision applying a 0.2% tax rate to idle land takes effect on July 1, 2027.
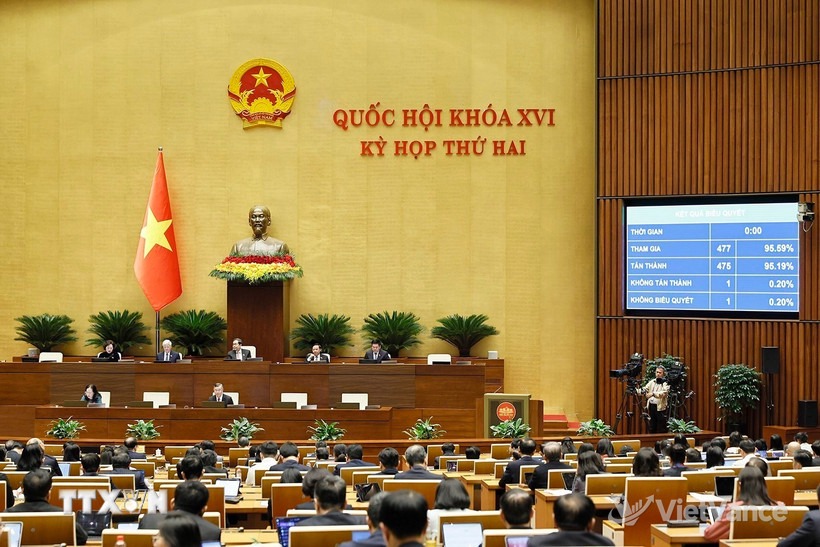
Vietnam’s National Assembly votes to pass amendments to the laws on corporate income tax, non-agricultural land use tax and personal income tax.(VietVance)
The amendments raise the revenue threshold at which businesses and individual business operators can choose a method for calculating corporate or personal income tax from VND 3 billion to VND 10 billion, effective from the 2027 tax year. They also authorize the government to adjust the threshold according to economic and social conditions in different periods. The amendments further provide a three-year corporate income tax exemption for small and medium-sized enterprises. The government will set the period for applying a tax calculation method in implementing regulations and specify that certain enterprises formed through mergers, splits or conversions are ineligible for the three-year exemption.
In education, the amendments provide corporate income tax incentives for public educational institutions and nonprofit private educational institutions. Vietnam’s Finance Minister Ngô Văn Tuấn said the nonprofit status of private institutions must be confirmed by the competent authority under the law. The government plans to limit the exemption in implementing regulations to income directly related to education and training, scientific research, and educational support services. Businesses and individual business operators supplying meals to educational and healthcare institutions are also covered by the relevant income tax exemptions.
The amendments also exempt land used by educational institutions for education and training from non-agricultural land use tax; land used for business, commercial or service purposes is excluded. Idle land will be taxed at 0.2%, with the taxable area based on the area left idle. The period for which land prices used to calculate non-agricultural land use tax remain fixed is proposed to be shortened from five years to three years. The related land price provisions will take effect on January 1, 2028.
Source: VietVance